Solid-State Batteries: The Final Push Toward Mass Production
2026-05-22
Solid-state batteries (SSBs) are approaching a pivotal stage. After years of research answering “Can we make them?”, the industry is now focused on “Can we produce them reliably at scale?” The period from 2026 to 2027 marks the first wave of pilot production and vehicle integration tests, with commercial deployment expected around 2030. Global investment in solid-state technology has already surpassed $20 billion, signaling a shift from feasibility studies to practical implementation timelines.
For energy storage, SSBs promise transformative advantages: theoretical cycle life exceeding 10,000 cycles, higher energy density, intrinsic safety, and adaptability across extreme temperature ranges. Some demonstration projects have even set targets for an equivalent energy cost as low as 0.2 CNY/kWh—approaching parity with current mainstream lithium iron phosphate (LFP) systems.
Technological Pathways: Sulfides, Oxides, and Polymers
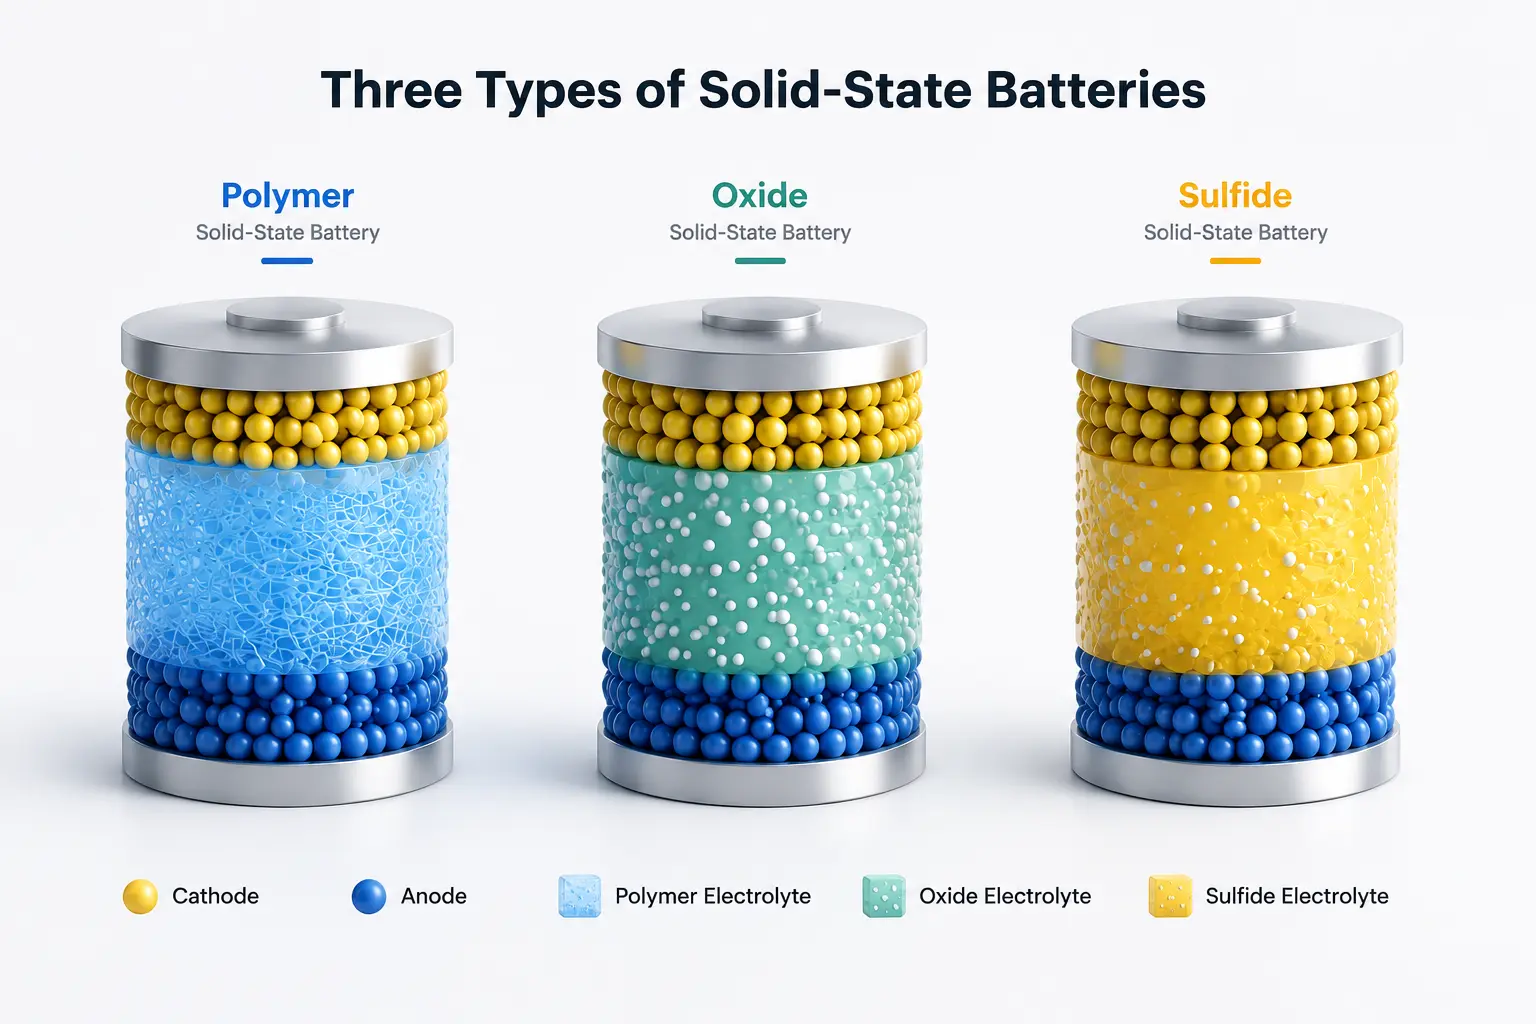
Solid-state batteries can be classified into three main routes based on electrolyte materials. Currently, semi-solid oxide-based batteries are commercially leading, while fully solid-state designs are gravitating toward sulfide electrolytes.
Sulfide Electrolytes: Leading Fully Solid-State Batteries
- Advantages: Sulfide electrolytes offer exceptional ionic conductivity (~10⁻² S/cm at room temperature), energy densities over 500 Wh/kg, low internal resistance, and strong interface contact.
- Challenges: Sensitive to moisture (can release H₂S), complex manufacturing processes, and high material cost (~1,000 CNY/kg for lithium sulfide).
- Industry Focus: Toyota, CATL, BYD, and Samsung SDI have all prioritized this path for mass production.
Oxide Electrolytes: Early Commercialization via Semi-Solid Batteries
- Advantages: Excellent thermal stability (>600 °C), compatibility with high-voltage cathodes, lower cost, and mature supply chains.
- Challenges: Lower ionic conductivity (~10⁻⁴ S/cm) and interface issues that can limit cycle life.
- Industry Focus: Companies like Weilan New Energy, Qingtao Energy, and Ganfeng Lithium have led semi-solid commercialization, with fully solid-state versions under development.
Polymer Electrolytes: Flexible, Niche Applications
- Advantages: Processable with existing lines, ideal for consumer electronics and drones, cost-effective.
- Challenges: Low room-temperature conductivity, requiring heating; energy density capped at ~300 Wh/kg.
Consensus: Semi-solid batteries remain transitional, while fully solid-state batteries are increasingly dominated by sulfide systems. Academic classifications identify three generations of SSBs, with the first (2025–2027) using graphite/low-silicon anodes achieving 200–300 Wh/kg.
Industrial Deployment and Timelines
The industrialization of SSBs follows a rhythm: semi-solid first, fully solid follows. Key company milestones illustrate the rapid pace.
| Company | Target | Latest Status |
|---|---|---|
| CATL | >500 Wh/kg, 1,500 cycles | Hefei pilot line operational; R&D team >1,000 |
| BYD | 480 Wh/kg, 5,000 km road test without thermal runaway | Chongqing 20 GWh production line launching in 2026 |
| Chery Auto | 400 Wh/kg mass, 600 Wh/kg lab; >1,500 km range; 6C fast charge | 0.5 GWh pilot line, continuous 60 Ah cell production |
| EVE Energy | 60 Ah cells for consumer & automotive | ≤5 MPa stable cycles, automotive-grade |
| Gotion High-Tech | 350 Wh/kg | 2 GWh mass line designed; pilot yield 90% |
| GAC Aion | 400 Wh/kg, 880 km range | First 5 GWh line operational |
| Toyota | — | Collaborating with Idemitsu; claims two-year lead |
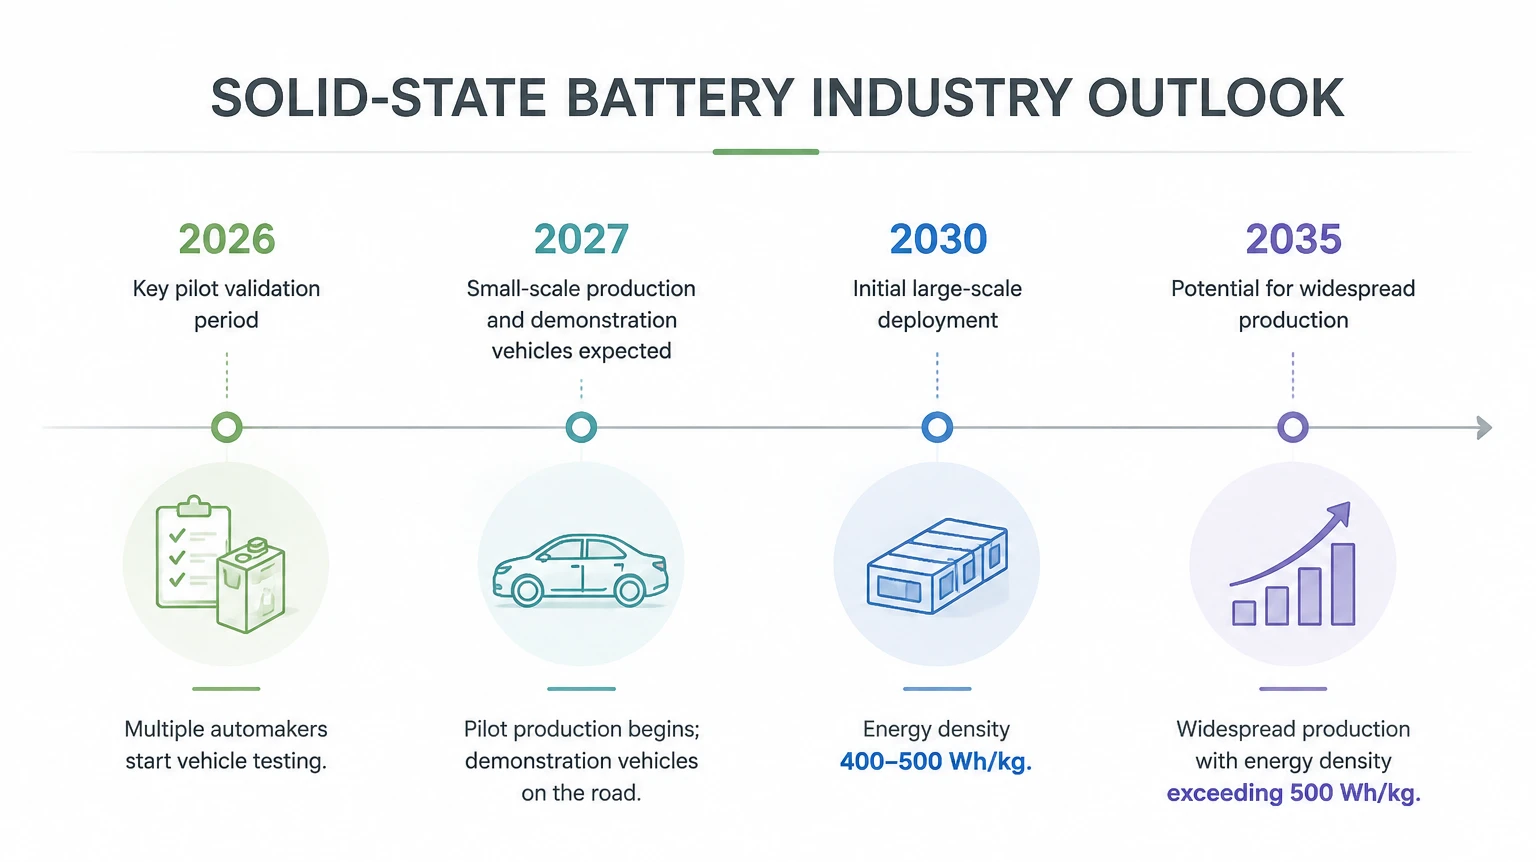
Industry Outlook:
- 2026: Key pilot validation period; multiple automakers start vehicle testing.
- 2027: Small-scale production and demonstration vehicles expected.
- 2030: Initial large-scale deployment, energy density 400–500 Wh/kg.
- 2035: Potential for widespread production exceeding 500 Wh/kg.
Investment and market projections indicate rapid expansion. By 2030, global SSB shipments are projected to exceed 200 GWh, with total solid-state battery shipments surpassing 700 GWh. Equipment value per GWh for SSBs reaches 400–500 million CNY, versus 100 million CNY for conventional liquid systems, predicting a global market of 107.94 billion CNY by 2030.
Key Challenges Before Mass Production
Four major technical hurdles remain:
1.Electrolyte stability
2.Composite cathode/anode stability
3.Thermal management of large-capacity cells
4.Electrode–electrolyte interface integrity
2.Composite cathode/anode stability
3.Thermal management of large-capacity cells
4.Electrode–electrolyte interface integrity
Laboratory performance does not directly translate to high-capacity cells; scaling challenges require extensive engineering. Cost is currently 3–5× that of liquid batteries (50–100× at the material level), but innovations may reduce it to 1.5× within a few years.
China leads in patents, with 14,400 SSB-related filings by 2025 (over 90% invention patents), representing 44% of newly disclosed global patents. Yet Japanese and Korean firms maintain an edge in foundational patents and core materials like sulfides, highlighting areas for further industrial breakthroughs.
Energy Storage Applications
SSBs offer unique advantages in energy storage:
- Safety: Nonflammable solid electrolytes eliminate thermal runaway risks. Demonstration cells survive puncture, short-circuit, overcharge, and compression tests without fire or explosion.
- Cycle Life: Storage systems exceed 10,000 cycles.
- Temperature Range: Suitable for cold regions; tantalum-doped LLZO SSBs retain 85% capacity at -20 °C and only 12% degradation after 500 cycles at 60 °C.
- Cost Efficiency: Demonstration projects target ≥90% energy efficiency and ≤0.2 CNY/kWh equivalent cost, matching mainstream LFP systems.
Industry adoption is already underway: CATL targets high-end storage, Weilan New Energy showcased SSBs at InterBattery 2026, and Yinpai Battery launched 587 Ah semi-solid storage cells with dedicated 6.5 GWh production lines.
Conclusion: Poised for Real-World Deployment
Solid-state batteries are in the final sprint from laboratory research to industrial-scale production. Beyond performance, they redefine safety standards and energy cost metrics. While large-scale deployment is expected in 3–5 years, pilot projects confirm technical feasibility, and "SSB + storage" systems are moving from concept to practical implementation.
Why Most Energy Storage Systems Never Use 100% DOD ?
What is a High-Voltage Direct-Connected PCS?